Tag: financial technology

  • EndowPay Wants to Make Digital Payments Easier for Nigerians Who Are Often Left Behind

    EndowPay Wants to Make Digital Payments Easier for Nigerians Who Are Often Left Behind

    For some Nigerians, sending money from a phone is a simple process. Open an app, select a beneficiary, enter an amount and confirm the transaction.

    But that experience assumes something that is not always true: that the person using the phone is comfortable navigating a financial app.

    For a market woman who can make a phone call but struggles to navigate a smartphone interface, digital banking can still feel inaccessible. For someone who is semi-literate or more comfortable communicating in a local language, the promise of financial technology can remain just that, a promise.

    This was the gap Okunola Orogun and the team behind EndowPay identified when they began building the fintech in November 2024.

    Rather than creating another payment app aimed primarily at digitally confident users, the company is focused on a different question: what would financial technology look like if it was designed around the people who find existing systems difficult to use? 

    Building for People Who Are Often Overlooked

    The conversation around financial inclusion in Africa has largely focused on bringing the unbanked into the formal financial system.

    But EndowPay believes access to a bank account is only one part of the problem.

    The bigger question is whether people can actually use the technology that gives them access.

    Okunola  describes people who may still depend on their children to operate their phones or walk to a POS terminal to send money to family members. For EndowPay, the existence of smartphones and digital payments should make these processes easier, not introduce another barrier.

    The company is therefore exploring natural-language interactions that allow users to communicate with financial technology in ways that feel more familiar.

    The idea is particularly relevant in a country where language, literacy and digital confidence can vary significantly across communities.

    If someone can make a phone call in their preferred language, Endow Pay believes they should eventually be able to use that same simplicity to carry out financial transactions.

    Making Payments Easier, Not Just Faster

    One of the company’s central arguments is that financial technology should remove friction from everyday transactions.

    The team points to a familiar situation. Imagine driving when a child calls to request ₦2,000 urgently. With a conventional banking app, the parent may need to stop, pick up the phone, open the application and complete the transfer.

    EndowPay is working toward a different experience through Endow Bot, which the company says is planned for rollout in Q4 2026.

    The proposed system would allow users to initiate transactions through a text and voice interaction, both in-app and on most popular instant messengers, supported by authentication layers designed to keep the process secure.

    The company’s focus on speed also extends to transaction processing. According to the team, EndowPay is working to make transactions complete within seconds, while its infrastructure is being designed to reduce the delays that customers often experience when payments fail.

    For Endow Pay, this is closely connected to trust.

    Trust Is Still the Biggest Challenge in Fintech

    Getting people to trust a company with their money is difficult, particularly for a young fintech competing against established financial institutions.

    The team says its approach has been to demonstrate value rather than simply talk about it.

    That includes focusing on transaction speed, customer support and reliability, while working with licensed partners to provide key financial services.

    EndowPay’s CTO says it works with CBN-licensed organisations for several of its services and has partnerships across banking and payment infrastructure. The company also says it has put compliance measures in place around anti-money laundering and data protection.

    The founders believe these relationships are important because trust in financial technology is not built through branding alone. It is built through the infrastructure behind the product and the consistency of the customer experience.

    Growth Built Around Active Users

    Since its alpha launch around September 2025, EndowPay says it has recorded steady user growth.

    But the team is less interested in accumulating large registration numbers than in understanding whether people actually use the product.

    Adebola says a significant majority of its current users are active, while the company has a customer retention team that reaches out to users to understand why they may have stopped using the platform and what could be improved.

    That feedback loop is becoming an important part of the company’s product development.

    The team says its upcoming V2 will further redefine the experience as it continues to build around the original goal of making financial technology more accessible.

    Building Without Chasing Funding

    Unlike many African fintech startups, EndowPay is currently 100% bootstrapped.

    The founders say this is intentional.

    Rather than raising capital and potentially adjusting the company’s direction around investor expectations, they want to build the core product and validate the original vision first.

    Okunola’s position is straightforward: funding should follow value rather than become the reason for building the company.

    The team remains open to investment in the future, but only from partners who understand and support the company’s direction.

    What Comes Next for EndowPay

    The company’s roadmap extends beyond consumer payments.

    According to EndowPay’s CTO, EndowPay is exploring a B2B offering that would allow SMEs to access business tools and maintain better financial records, potentially helping them when seeking financing or managing their operations.

    The team is also looking at cross-border payments, remittance services, virtual cards and cross-border accounts that could make it easier for remote workers and businesses to receive money internationally.

    On the infrastructure side, EndowPay is developing transaction routing technology designed to direct payments through available providers and reduce transaction failures.

    The broader ambition is to make financial technology feel less complicated for the people using it.

    For EndowPay, the opportunity is not simply to become another fintech competing for the same digitally savvy customers.

    It is to rethink how financial technology can work for people who have historically been expected to adapt to the technology, rather than having the technology adapt to them.

    And as Nigeria’s financial ecosystem becomes increasingly digital, that distinction could become increasingly important.

    This article is based on an interview with Okunola Orogun and EndowPay’s team conducted by African Tech Journal.
  • African Tech Stopped Racing and Now It is Acquiring

    African Tech Stopped Racing and Now It is Acquiring

    What 67 deals in a single year tells you about where African tech is actually headed.

    For most of the last decade, the dominant logic in African tech was simple: raise, expand, repeat. Startups competed for market share in fragmented markets, grew headcount faster than revenue, and treated the next funding round as both validation and lifeline.

    The playbook rewarded ambition over discipline, and for a while, capital was available enough to make it work. The 2025 numbers say that era is done and over. African startups recorded 67 merger and acquisition deals across the continent in 2025, the highest annual total ever, a 72% increase from the 39 deals recorded in 2024, and well above the previous record of 40 deals set in 2022. Total funding also grew, reaching $3.4 billion across 502 deals, up 44% year-on-year.

    However fewer deals received more capital, meaning money is concentrating rather than spreading. The ecosystem is not just growing, it is narrowing deliberately around the companies that have proven they can survive. 

    What changed is not just the volume of deals, but the character of them. In earlier years, acquisitions in African tech were largely distress events, a struggling startup selling to avoid a disorderly shutdown.

    The recent wave looks different, well-capitalised companies use acquisitions to buy capabilities they could have built but chose not to wait for, to enter markets without the cost of building from zero, and to secure regulatory licences that would otherwise take years to obtain.

    The deal logic shifted from rescue to strategy, the deals themselves tell the story clearly, Flutterwave acquired Mono; Nigeria’s leading open banking infrastructure provider  in a transaction valued between $25 million and $40 million, folding identity verification, account connectivity, and bank payment capabilities directly into its own stack. One deal turned a competitor relationship into an internal capability.

    Moniepoint moved on two fronts in quick succession: first acquiring Orda, a cloud-based restaurant management platform, to deepen its merchant tooling, then completing a 78% stake acquisition in Kenya’s Sumac Microfinance Bank, a 20-year-old licensed institution to enter East Africa without waiting for new licences the Central Bank of Kenya had frozen.

    South African infrastructure firm Stitch made two acquisitions of its own: ExiPay in January and Efficacy Payments in July, each designed to internalise critical payment rails rather than depend on third parties. Paystack absorbed Ladder Microfinance Bank in Nigeria for similar reasons.

    Twiga Foods in Kenya acquired three distributors to own more of its own supply chain. These were not opportunistic moves. They were deliberate vertical integrations by companies that had decided owning the infrastructure mattered more than partnering with it. 

    Fintech led the wave by some distance, accounting for nearly 46% of all deals in 2025, that concentration is not accidental. Fintech in Africa operates in one of the most regulation-dense environments on the continent. Licences are difficult to obtain, compliance costs are rising, and regulators in Nigeria, Kenya, and South Africa have become more assertive. In that environment, acquiring a company that already holds the right licence in the right market is not just convenient, it is often the only realistic path to expansion at speed.

    Analysts have begun calling this pattern “licence hunting”: acquisitions driven less by customer bases or product fit, and more by the regulatory permissions the target already holds. 

    It is necessary to state that not every company that tried to participate in this wave succeeded, several startups entered acquisition talks in 2024 and 2025, found no takers, and shut down.

    The market has become selective, acquirers are looking for clean governance, clear unit economics, and genuine strategic fit. Distress alone is not enough to close a deal and that selectiveness is itself a sign of maturity.

    African tech M&A has grown up enough to be discriminating. What the data points toward is a smaller number of dominant platforms emerging across the continent’s major markets, companies with vertical integration, cross-border reach, and regulatory moats that make them difficult to displace.

    TechCabal Insights projected the formation of three to four dominant multi-country platforms controlling payments, logistics, and digital banking across multiple African countries by the end of 2026.

    For founders building today, this is the new context. The blitzscaling playbook: raise aggressively, grow fast, figure out the economics later has been replaced by a simpler and harder question: what do you own, and is it worth owning? The companies that can answer that clearly are the ones getting acquired or doing the acquiring. The ones that cannot are the ones disappearing quietly.

    The land grab produced a generation of African startups, the consolidation era will determine which ones actually last.

    Sources:

    1. TechCabal Insights, State of Tech in Africa 2025 — https://insights.techcabal.com/state-of-tech-in-africa-2025-from-growth-at-all-costs-to-sustainable-scale/
    2. TechCabal, Flutterwave-Mono — https://techcabal.com/2026/01/06/aquisitions-in-africas-tech-ecosystem-in-2025/
    3. TechCabal, Moniepoint-Orda and Moniepoint-Sumac — https://techcabal.com/2026/03/26/nigerias-moniepoint-enters-kenya-with-78-stake-in-sumac-microfinance/
    4. BusinessDay, Moniepoint-Sumac — https://businessday.ng/technology/article/nigerias-moniepoint-enters-kenya-through-sumac-acquisition-targeting-sme-lending-boom/
    5. TechPoint, Stitch-Efficacy Payments — https://techpoint.africa/news/stitch-acuires-efficacy-payments/
  • Why Chowdeck is the Unsung Hero of Lagos Hustle Culture

    Why Chowdeck is the Unsung Hero of Lagos Hustle Culture

    Before Chowdeck showed up, ordering food without bleeding money on delivery fees or waiting two hours felt like a fairy tale.

    Bike men would quote you 5k to cross two neighbourhoods, Jumia Food, and the others slapped ridiculous charges on every order, and most times your jollof still arrived cold.

    Then Chowdeck landed in Lagos and quietly changed the game.

    Chowdeck isn’t just another delivery app, it’s a community of riders, restaurants, and everyday hustlers who finally made “quick and cheap” mean something real.

    In a city where traffic can swallow three hours of your life without warning, being able to get a full plate of egusi and pounded yam (or shawarma, or indomie deluxe) delivered for as low as ₦600 is revolutionary.

    That’s cheaper than the okada you’d take to the buka and back, and you can get free deliveries and a couple other freebies with a members subscription starting at just ₦3,500 a month.

    I’m the typical Lagos creative: 14-hour workdays, back-to-back Zoom calls, deadlines breathing down my neck.

    The moment hunger hits, my brain wants to shut down. Stepping out isn’t an option. Lagos traffic doesn’t care about your client presentation at 4 pm.


    Cooking? I love my kitchen, but not when I’m in the zone. Chowdeck became my lifeline.

    I’ve ordered from Chicken Republic in Ikorodu to my house in Federal Low Cost Housing Estate at 7:47 pm and had hot food in my hands by 8:09 pm. Two thousand five hundred naira total, including delivery. Try doing that with any other platform in 2019–2021.

    But it’s bigger than my personal convenience. Chowdeck created real jobs for thousands of young riders who now earn daily without needing a “connection” or university degree.

    Restaurants that were barely surviving now get orders from customers 30 minutes away, they would never have reached. Small businesses think that a woman making killer asun in Surulere or the guy doing moi-moi and akara in Ajah can now list on Chowdeck and blow up overnight.

    In a continent where logistics remains one of the biggest barriers to everything (e-commerce, healthcare, you name it), Chowdeck proved you can build hyper-efficient last-mile delivery that actually works for African wallets and African chaos.

    They’re in Morocco, Kenya, Uganda, Ghana, Côte d’Ivoire, and still flying under the radar while the spotlight stays on fintech unicorns.

    Chowdeck deserves way more flowers. In the middle of Lagos madness, they made it possible for us to stay locked in, eat well, and keep creating without breaking the bank or wasting half the day. If that’s not proper African innovation, I don’t know what is.

  • The African Tech Brand Quietly changing lives : Paystack

    The African Tech Brand Quietly changing lives : Paystack

    When I think about the African tech brand that has quietly made life easier for thousands of creatives, small business owners, and dreamers like me, Paystack is the first name that comes to mind. It’s funny because I didn’t start out paying attention to fintech at all.

    I just wanted to understand why so many business pages on Instagram were suddenly taking payments smoothly without all the usual back-and-forth. Somewhere along the line, the answer kept pointing back to one company: Paystack.

    My first real interaction with the brand wasn’t even as a business owner. It was as a customer. I remember trying to pay for a virtual class and expecting the usual stress-failed transactions, double debits, or the “network not available” message.

    But the payment went through instantly, and the receipt hit my email before I could even refresh the page.

    It was such a small moment, but it made me pause. In this country, where simple things often become complicated, that small moment of ease meant something.

    The more I paid attention, the more I realized how deeply Paystack is woven into the daily hustle across Africa.

    The vendors who rely on payment links. The creators who send invoices. The startups that feel “official” because they have a proper checkout page. Even NGOs and schools use it now.

    Paystack somehow manages to be present but not loud , almost like a quiet backbone that keeps so many ideas alive.

    What I love most is how simple they make things feel. You don’t need to be tech-savvy to use it. You don’t need a big business. You don’t even need a website.

    There’s something empowering about that the idea that anyone with a skill or a passion can start collecting payments and building something real.

    And of course, the global recognition they’ve gotten, especially after their acquisition by Stripe, made me genuinely proud. It felt like a win for everyone who believes Africa can build world-class technology.

    But beyond the headlines and the milestones, Paystack represents something personal to me: possibility.

    The possibility that African problems can be solved by African innovators. The possibility that a simple idea can transform how we work and create.

    Paystack may be a fintech company, but to me, it’s a reminder that progress doesn’t always have to be loud. Sometimes, it’s the quiet systems running in the background that change the most lives.

    That’s why Paystack is the tech brand I love.

  • Chams Mobile is quietly building real solutions for Nigeria

    Chams Mobile is quietly building real solutions for Nigeria

    I still remember the first time someone mentioned Chamsmobile to me. It was during a casual conversation about digital payments and identity systems in Nigeria, and a friend said, “Have you checked what Chamsmobile is doing?

    They are not loud, but they’re doing real work.” Out of curiosity, I went online to see for myself, and honestly, that small search opened my eyes to a brand that deserves far more attention than it gets.

    What I love about Chamsmobile is that they are building solutions for realities we face every day in this country, not fantasies.

    Many tech companies chase hype; Chamsmobile builds quietly for people who need technology the most: market women, transport workers, SMEs, civil servants, and communities usually left out of the main conversation.

    One thing that really stood out to me is their focus on digital identity and financial inclusion. In a country where a simple thing like verifying someone’s identity can delay jobs, stop access to credit, or complicate business transactions,

    Chamsmobile found a way to simplify it with their Kegow platform. It’s not just about transferring money. It’s about helping people prove who they are, opening accounts easily, and accessing financial services without stress.

    I also respect how they operate. They don’t try to be everywhere at once; instead, they focus on solving real administrative and financial gaps in Nigeria.

    For example, the way they’ve built partnerships with government agencies and private organizations shows that they understand the Nigerian system deeply. They’ve also created room for agents and small business owners to earn through their digital services, and for me, that’s one of the most practical ways a tech brand can empower ordinary people.

    Another thing I admire is the trust they’ve built over the years. In a space where many fintechs rise fast and crash even faster, Chamsmobile is consistent.

    They don’t make noise, but they deliver. They’ve been part of Nigeria’s digital identity journey long before it became trendy, with the help of their parents’ company, Chams Hold Co, and they’ve stayed committed to it through every challenge.

    Chamsmobile makes me proud because they represent what African tech should be: innovation rooted in real problems, solutions created with Nigerians in mind, and a quiet confidence that speaks louder than hype. They may not always trend on social media, but they are impacting lives in a way that truly matters.

    For me, that’s the kind of tech brand worth celebrating.

  • The African Fintech Library: Preserving the Institutional Memory of a Continent in Motion

    The African Fintech Library: Preserving the Institutional Memory of a Continent in Motion

    In the African tech ecosystem, the greatest barrier to scale isn’t always capital or talent: it’s the “Knowledge Gap.”

    For a decade, the “how-to” of African fintech has existed in silos. Valuable lessons on navigating the Central Bank of Nigeria (CBN), managing cross-border liquidity in the EAC, or scaling credit in South Africa are often trapped in private WhatsApp groups or lost when an operator switches roles.

    Today, Builders in Fintech are changing that. With the launch of the African Fintech Library (AFL), the ecosystem finally has a structured, durable archive for the hard-won lessons of its builders.

    Beyond the Informal: Why Structure Matters

    The AFL didn’t emerge from a vacuum. It was born from a recurring observation: Africa’s fintech sector is projected to grow 5x by 2028, yet its “institutional memory” is scattered.

    “Valuable operational and regulatory lessons are being generated every day,” the AFL team notes. “But they are rarely captured in a format that outlives the moment.”

    The Library is the intentional answer to this problem. It is designed to preserve knowledge before it disappears, making it accessible to a founder in Senegal who needs to understand the compliance mistakes made by a predecessor in Ghana.

    One Archive. 10,000 Practical Insights.

    The vision for the AFL is as bold as the sector it serves. It isn’t just a blog; it is a Structured Knowledge Infrastructure.

    Think of it as the “Reference Manual” for the African context. The Library covers the critical, often unglamorous, pillars of the industry:

    • Payments & Infrastructure: The “plumbing” of how money actually moves across borders.
    • Regulation & Governance: Navigating the shifting sands of continental policy.
    • Risk & Credit: Managing the math behind Africa’s lending boom.

    Built by Practitioners, for Builders

    The most distinctive feature of the AFL is its authorship. Every guide is written by real world practitioners, the people who have sat in the rooms where the decisions were made.

    By moving from “theory” to “hands-on experience,” the AFL levels the playing field. Emerging talent and first-time founders no longer need to rely solely on “private circles” to understand the nuances of the market. They now have a central publication that offers expert knowledge backed by thorough research and lived experience.

    A Call to the Ecosystem: Contribute Your Story

    The AFL is a living asset. As the ecosystem evolves, so must the Library. The team is calling on builders across the continent to share their practical knowledge.

    The process is rigorous but rewarding:

    1. Write: Draft a publication ready guide based on a topic you know in theory and practice.
    2. Submit: Your work undergoes a 2–4 week review by the Builders in Fintech editorial team.
    3. Preserve: Once live, your insights become a permanent part of the continent’s fintech history.

    The ATJ Perspective: Why We Are Amplifying This

    At African Tech Journal, we believe that Structured Knowledge = Faster Innovation. The launch of the African Fintech Library marks a new dispensation. It is the moment the African fintech sector stops “reinventing the wheel” and starts building on a foundation of collective intelligence. Whether you are an operator looking to build faster or a student looking to understand the mechanics of money, the AFL is now your primary reference.

    Start Exploring the Archive Today

    Don’t build in the dark. Access the collective memory of the continent’s best builders.

    Visit: www.buildersinfintech.com/afl


  • I said goodbye to scam exchangers, a Raenest app story

    I said goodbye to scam exchangers, a Raenest app story

    N500/$ is the rate I’ll use to exchange the funds. Na my account you take collect am.”

    If you’ve freelanced since the days of oDesk and Elance, you’ll recognise this. It’s what so-called exchangers say to freelancers trying to receive payments from clients worldwide.

    Some exchangers are honest, but many are crooks. They take a large cut of freelancers’ earnings or scam them entirely. It’s shocking!

    I fell victim for years. Freelance platforms then updated to allow direct deposits to Africa. FinTech companies like Raenest emerged, enabling us to be paid in any currency.

    Raenest has addressed the scammer-exchanger issue with popular ACH accounts and useful virtual cards.

    Here are five reasons why I believe they will continue to thrive:

    Timely Free Deposit Offers: I’ve signed up with other fintech companies, but none have offered free payment deposits. My ‘grey’ matter just doesn’t have any memory of it 🙂


    Since joining Raenest, I’ve received many free deposit offers. FinTechs usually charge fees for operational costs and regulations. But with Raenest, my USD, GBP, or EUR deposits periodically come in full, with no fees.

    This shows their commitment to helping global earners keep every cent. I think it’s their most thoughtful ‘gift’ and one of the things I love about the them.

    Cross-border Payments: The distance between Europe and Africa is about 14 kilometers. Although people like Pelumi Nubi have crossed the borders using just their cars, 14km is still a far stretch. Let’s not even fact-check the for America to Africa. Yet, we can send and receive money without traveling that distance! Whether you’re a freelancer or a business in Africa needing payments from the UK, US, or China, Raenest has you covered.

    Stablecoin Integration: Many freelancers want to earn in coins like Ethereum or Tron to handle exchange rate changes. Raenest surprised everyone by announcing stablecoin accounts!

    If you have a USD account, you can easily create a stablecoin wallet. Receive payments in USDT or USDC with competitive exchange rates. Exciting, right? 🤭

    Virtual Cards: Using a virtual credit card has never been cheaper. With Raenest, you can get a virtual card for at a low fee. Fund it easily and use it for subscriptions, courses, or ads!

    Bella’s Exclusive Perks: Raenest has launched ‘Raenest Perks’. This offers special discounts for freelancers and business owners. Whether you need groceries or the latest Adidas shoes at 15% off, Raenest is your go-to.

    In conclusion, business development is key to success. Raenest understands its customers and continues to develop strategies to meet their needs.

    If you’re a freelancer, content creator, or running a business in Africa, visit Raenest today at www.raenest.com. Enjoy hassle-free payments and send money to over 40 countries!

  • Not all tech brands are app or fintech, Meet Mozzi Pizza, a Kigali digital dining game changer

    Not all tech brands are app or fintech, Meet Mozzi Pizza, a Kigali digital dining game changer

    Mozy Pizza Remera–Gisimenti

    When people talk about African tech brands, they usually mention apps, fintech startups, or mobility companies.

    But for me, one of the most impressive tech-driven brands I use almost every week is Mozy Pizza, right in Remera–Gisimenti, Kigali.

    It’s more than a restaurant, it’s a smooth digital experience that makes ordering food in the city feel modern, fast, and stress-free.

    My relationship with Mozy Pizza started on a busy afternoon when I didn’t have time to leave work. A friend told me, “Just order it on Vuba Vuba.” I tried it once… and now it’s my go-to for pizza, burgers, shawarma, and even their surprisingly good coffee. What keeps me loyal isn’t just the food, it’s how technology connects everything, from ordering to payment to fast delivery.

    The first thing I love about Mozy Pizza is how easy it is to order online. Whether I’m at home or at school, I open Vuba Vuba, choose what I want, and confirm. No calling, no waiting, no miscommunication.

    Their menu is always updated, and I can track my order in real time. For a city like Kigali that’s growing quickly, that level of convenience matters.

    Payments are another thing they’ve nailed. Mozy accepts Mobile Money, Visa cards, and other digital options.

    This makes it simple for anyone, whether you prefer MoMo or card payments, to check out in seconds. It feels like the brand truly understands how young Rwandans live: cashless, online, and always on the move.

    And of course, we have to talk about delivery. Mozy Pizza delivers across Kigali, and they are consistently fast.

    Even during peak hours, I get updates, and the riders always arrive with warm food. That reliability is one of the reasons I consider Mozy a tech-enabled brand worth celebrating. They have blended good food with the right digital tools to solve a real problem: getting quality meals quickly and conveniently in a busy city.

    In a market where many restaurants still rely on traditional methods, Mozy Pizza stands out by embracing technology to improve customer experience.

    It may not look like a typical “tech company,” but the way it operates — online ordering, digital payments, and efficient delivery — is exactly what modern African consumers need, and one thing I have noticed is that they are also liked by internationals like Nigerians, Indians, Europeans and those one comes from alba ,, their menu is preferable.

    For me, Mozy Pizza is more than a place that makes great pizza. It’s a perfect example of how technology can transform everyday services and make life easier.

    That’s why it’s the African tech-powered brand I genuinely love.

  • My first dividend alert from Bamboo changed everything

    My first dividend alert from Bamboo changed everything

    I got a credit alert on Friday, and it completely surprised me. At first, I thought it was just a random notification. But when I checked properly, I realized it was my first-ever dividend payout, from one of the stocks I invested in through Bamboo.

    That small moment made everything feel real, like, “Wow, I’m actually investing.”

    My interest in investing started about two years ago, even though I didn’t fully understand it then. Last year at my former workplace, a few of us, the ladies, got into a conversation about savings, wealth-building, and different investment apps.

    Someone mentioned Bamboo, and we all downloaded it on the spot. We tried setting it up that day, but something came up for me, and I didn’t complete my registration. The excitement faded, and life moved on.

    Earlier this year, I started seeing people on X (Twitter) talk about investment again. I love reading those conversations, especially when they break things down in simple ways.

    Bamboo kept coming up, and because I had interacted with it before, I decided to go back to it. This time, I completed my setup and began investing, even though I wasn’t fully consistent and didn’t understand everything at first.

    What made it easier is how simple the Bamboo app is.

    The interface is clean, clear, and beginner-friendly. You can see your stocks, track your money, and understand what’s happening without feeling confused. And even though I didn’t learn from any official community, I picked up so many helpful tips from regular people sharing their experiences on X, things like how dividends work or how to navigate certain features.

    But nothing prepared me for the feeling of seeing that dividend alert on Friday. The amount wasn’t the point.

    What mattered was the realization that something I invested in actually grew and returned value. It felt like a small victory, but a very meaningful one.

    Bamboo stands out to me because it makes investing accessible. It brings global stocks closer and makes the whole process simple enough for anyone who is just starting the journey.

    And that first dividend? It gave me the motivation to keep going.

  • Lumi business -an idea to 400,000 monthly sales transactions in peak periods

    Lumi business -an idea to 400,000 monthly sales transactions in peak periods

    It started during COVID, when movement was restricted, and many of us finally had time to think deeply about the structural problems facing African businesses.

    There were four of us at the beginning. We met roughly once a month, not to rush into building a startup, but to talk through patterns we were seeing in the market. One issue kept resurfacing. Most businesses in Nigeria were operating with very little data and almost no modern tools to guide day-to-day decision making.

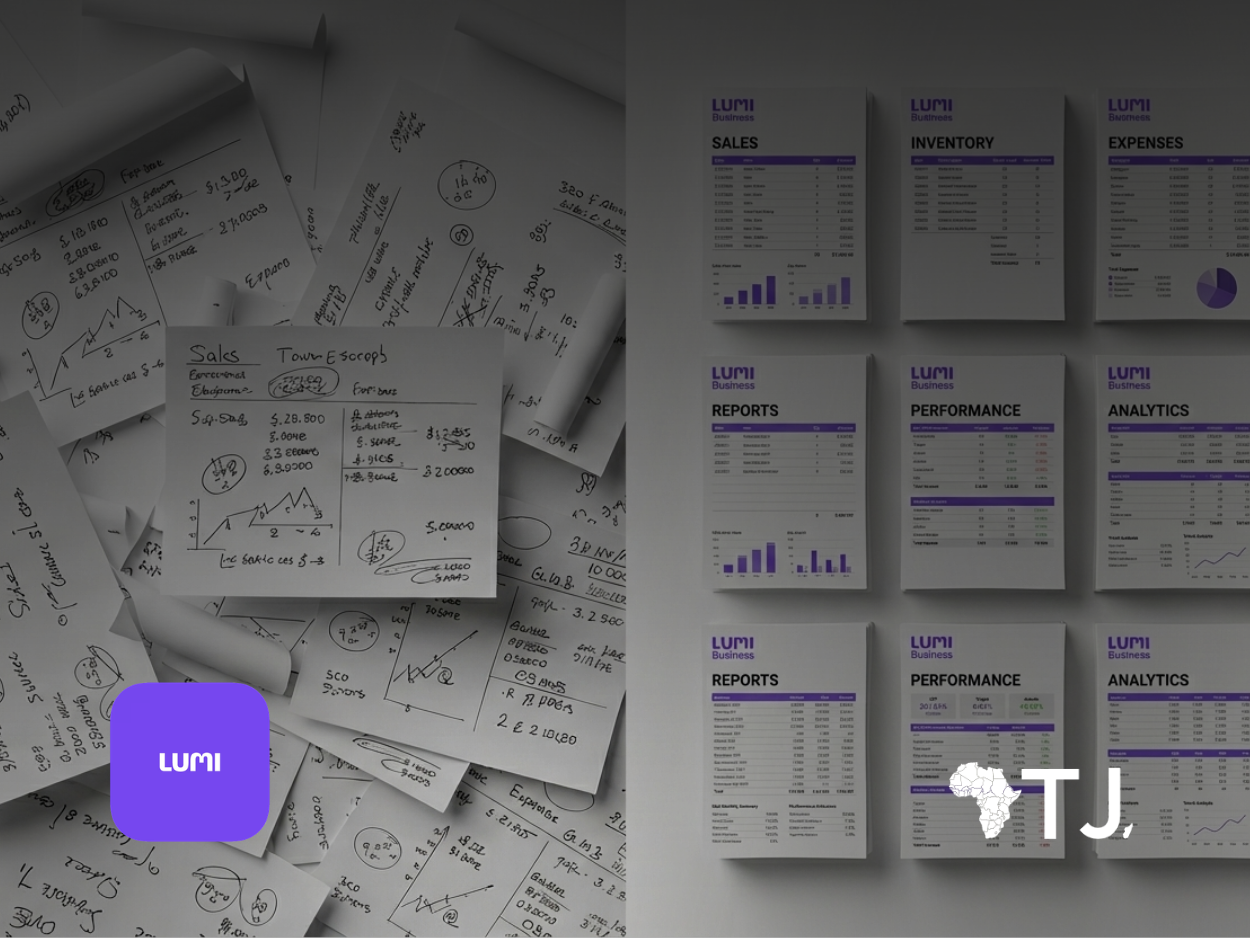
    At the time, many startups were focused almost entirely on payment collection. That mattered, but it felt incomplete. Collecting money is only one part of running a business. Inventory, expenses, reporting, and performance visibility were still largely unmanaged. Businesses were working hard, but without clarity.

    That gap became the foundation of Lumi Business.

    After Payments, Businesses Were Left Alone

    Speaking directly with business owners shaped our conviction. Again and again, we saw that once payments were collected, owners were largely left on their own. Many relied on foreign software that was not built for Nigeria. Others stitched together fragmented local tools that never worked as a single system.

    The result was predictable. Decisions were made based on instinct rather than insight. Owners put in effort without knowing what was truly working. That disconnect between effort and clarity pushed us into this space.

    We did not want to build another narrow solution. We wanted to help businesses actually run better.

    Starting With People and Patience

    We started with a technically strong founding team, most of us with engineering backgrounds. Several of us had worked in structured retail and manufacturing environments like KraftHeinz and Pepsi, as well as tech startups serving small and medium businesses. Those experiences shaped how we thought about systems, efficiency, and scale.

    On the capital side, we raised a small friends and family round. It allowed us to build an early product, test with real merchants, and iterate quickly without external pressure. Family and close friends were critical, not just financially, but emotionally. Their belief gave us the patience to build deliberately and stay focused on real customer problems.

    Trust, Pricing, and Market Reality

    Early challenges were unavoidable. The first was trust. Convincing business owners to move critical operations onto a new platform takes time. The second was hiring, especially in an environment where experienced talent often had safer or better-paying options.

    Pricing was another constraint. Nigerian businesses are highly price sensitive, and we could not charge what similar tools cost in Europe or North America, even though development costs were comparable. Inflation and currency instability made long-term planning difficult.

    Interestingly, recent tax reforms shifted behaviour. More businesses began to understand the importance of proper record keeping and structured systems. That shift aligned closely with what we were building.

    Technology as the Foundation

    Lumi was technology-first from day one. We were not a traditional business that later adopted tech. Technology was the lever for scale, consistency, and insight.

    We built an all-in-one platform combining sales, inventory management, payments, expenses, customer management, analytics, and integrations with financial partners. Internally, strong data infrastructure and scalable cloud systems allowed us to support hundreds of merchants across multiple locations.

    Once customers got past the learning curve, many became deeply reliant on the visibility and control the platform provided. Over time, Lumi shifted from being a nice-to-have to being operationally essential.

    Growth, Impact, and What Endures

    At our peak, we were processing over 400,000 sales transactions monthly and more than ₦11 billion in transaction value across hundreds of merchants. Beyond scale, we are proud that we built a profitable, sustainable business solving real operational problems.

    As customers matured, their questions changed. They began asking about margins, trends, and optimisation. Access to data was reshaping how they thought about their businesses.

    Through it all, certain principles remained non-negotiable. Treat the team fairly. Reward hard work. Champion the customer. Build patiently.

    Looking ahead, the focus is on scaling through aligned partnerships and ensuring technology remains digestible for business owners used to manual systems. As AI reshapes competitive advantage, structured data will be the entry point. That is where Lumi’s foundation matters most.

    It feels like we have only scratched the surface.