Category: Fintech

Financial technology, mobile money, digital banking, payment solutions, and financial inclusion

  • EndowPay Wants to Make Digital Payments Easier for Nigerians Who Are Often Left Behind

    EndowPay Wants to Make Digital Payments Easier for Nigerians Who Are Often Left Behind

    For some Nigerians, sending money from a phone is a simple process. Open an app, select a beneficiary, enter an amount and confirm the transaction.

    But that experience assumes something that is not always true: that the person using the phone is comfortable navigating a financial app.

    For a market woman who can make a phone call but struggles to navigate a smartphone interface, digital banking can still feel inaccessible. For someone who is semi-literate or more comfortable communicating in a local language, the promise of financial technology can remain just that, a promise.

    This was the gap Okunola Orogun and the team behind EndowPay identified when they began building the fintech in November 2024.

    Rather than creating another payment app aimed primarily at digitally confident users, the company is focused on a different question: what would financial technology look like if it was designed around the people who find existing systems difficult to use? 

    Building for People Who Are Often Overlooked

    The conversation around financial inclusion in Africa has largely focused on bringing the unbanked into the formal financial system.

    But EndowPay believes access to a bank account is only one part of the problem.

    The bigger question is whether people can actually use the technology that gives them access.

    Okunola  describes people who may still depend on their children to operate their phones or walk to a POS terminal to send money to family members. For EndowPay, the existence of smartphones and digital payments should make these processes easier, not introduce another barrier.

    The company is therefore exploring natural-language interactions that allow users to communicate with financial technology in ways that feel more familiar.

    The idea is particularly relevant in a country where language, literacy and digital confidence can vary significantly across communities.

    If someone can make a phone call in their preferred language, Endow Pay believes they should eventually be able to use that same simplicity to carry out financial transactions.

    Making Payments Easier, Not Just Faster

    One of the company’s central arguments is that financial technology should remove friction from everyday transactions.

    The team points to a familiar situation. Imagine driving when a child calls to request ₦2,000 urgently. With a conventional banking app, the parent may need to stop, pick up the phone, open the application and complete the transfer.

    EndowPay is working toward a different experience through Endow Bot, which the company says is planned for rollout in Q4 2026.

    The proposed system would allow users to initiate transactions through a text and voice interaction, both in-app and on most popular instant messengers, supported by authentication layers designed to keep the process secure.

    The company’s focus on speed also extends to transaction processing. According to the team, EndowPay is working to make transactions complete within seconds, while its infrastructure is being designed to reduce the delays that customers often experience when payments fail.

    For Endow Pay, this is closely connected to trust.

    Trust Is Still the Biggest Challenge in Fintech

    Getting people to trust a company with their money is difficult, particularly for a young fintech competing against established financial institutions.

    The team says its approach has been to demonstrate value rather than simply talk about it.

    That includes focusing on transaction speed, customer support and reliability, while working with licensed partners to provide key financial services.

    EndowPay’s CTO says it works with CBN-licensed organisations for several of its services and has partnerships across banking and payment infrastructure. The company also says it has put compliance measures in place around anti-money laundering and data protection.

    The founders believe these relationships are important because trust in financial technology is not built through branding alone. It is built through the infrastructure behind the product and the consistency of the customer experience.

    Growth Built Around Active Users

    Since its alpha launch around September 2025, EndowPay says it has recorded steady user growth.

    But the team is less interested in accumulating large registration numbers than in understanding whether people actually use the product.

    Adebola says a significant majority of its current users are active, while the company has a customer retention team that reaches out to users to understand why they may have stopped using the platform and what could be improved.

    That feedback loop is becoming an important part of the company’s product development.

    The team says its upcoming V2 will further redefine the experience as it continues to build around the original goal of making financial technology more accessible.

    Building Without Chasing Funding

    Unlike many African fintech startups, EndowPay is currently 100% bootstrapped.

    The founders say this is intentional.

    Rather than raising capital and potentially adjusting the company’s direction around investor expectations, they want to build the core product and validate the original vision first.

    Okunola’s position is straightforward: funding should follow value rather than become the reason for building the company.

    The team remains open to investment in the future, but only from partners who understand and support the company’s direction.

    What Comes Next for EndowPay

    The company’s roadmap extends beyond consumer payments.

    According to EndowPay’s CTO, EndowPay is exploring a B2B offering that would allow SMEs to access business tools and maintain better financial records, potentially helping them when seeking financing or managing their operations.

    The team is also looking at cross-border payments, remittance services, virtual cards and cross-border accounts that could make it easier for remote workers and businesses to receive money internationally.

    On the infrastructure side, EndowPay is developing transaction routing technology designed to direct payments through available providers and reduce transaction failures.

    The broader ambition is to make financial technology feel less complicated for the people using it.

    For EndowPay, the opportunity is not simply to become another fintech competing for the same digitally savvy customers.

    It is to rethink how financial technology can work for people who have historically been expected to adapt to the technology, rather than having the technology adapt to them.

    And as Nigeria’s financial ecosystem becomes increasingly digital, that distinction could become increasingly important.

    This article is based on an interview with Okunola Orogun and EndowPay’s team conducted by African Tech Journal.
  • How a University-Era Bookkeeping Business Became TELA, a Business Intelligence Platform for SMEs

    How a University-Era Bookkeeping Business Became TELA, a Business Intelligence Platform for SMEs

    For many small business owners, running a business means juggling sales, payments, invoices, customers, expenses and a long list of daily tasks, often without having a clear picture of what the numbers actually mean.

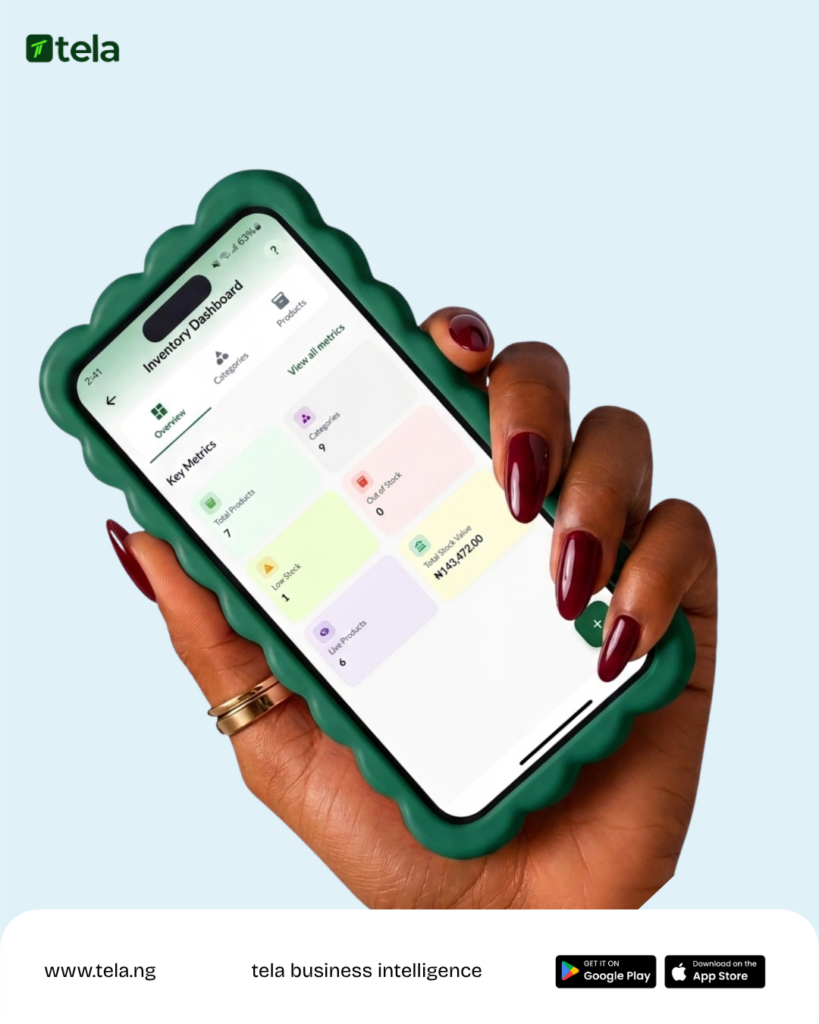
    This was the problem that led to Tela, a business intelligence platform designed to help small businesses and freelancers not only digitise their operations, but understand what is happening inside their businesses.

    Tela’s journey, however, did not start as a technology company.

    From managing books to building a platform

    Tela’s story began in 2021 when its founder, Adeyemo Damilare, started Rux Finance after graduating from university as a finance graduate. The business helped small businesses manage their finances, organise their books and make sense of their financial activities.

    As the business grew, so did the workload.

    What initially could be managed with manual processes eventually became too much to handle with what the team described as “pen and paper.” That experience became the starting point for a bigger question: what if these processes could be turned into a product?

    Damilare Adeyemo brought in James Dauda , Aaron Daudu and Jumoke Ajayi, who he had known for about 10 years, and together they began working on the idea at a larger scale.

    What emerged was Tela, evolving from a financial management solution into a business intelligence platform for small businesses and entrepreneurs.

    “We went a step further. Not just digitalizing their product or digitalizing their business, but also making it make sense,” the team explained during an interview with African Tech Journal.

    Building around how entrepreneurs actually work

    One of Tela’s early challenges was not necessarily figuring out what features to build, but deciding what should not be built.

    For the team, small businesses already operate within established habits. Many entrepreneurs rely heavily on WhatsApp, conversational selling and other familiar platforms to manage their businesses.

    The challenge was therefore to introduce technology without forcing entrepreneurs to completely change the way they work.

    “It’s easy to build a product with too many features,” the team said. The harder task was figuring out what an entrepreneur actually needs to see, what should be automated, what should be explained and what should be left untouched.

    This led the team to spend time speaking with customers, vendors and other business owners, while conducting market research to understand their behaviours and expectations.

    That approach has continued to shape Tela’s product.

    Moving beyond digitalisation with AI

    Tela initially operated as a web-based product, offering tools such as invoicing, receipts and payment links. The company has since shifted its focus towards its Android and iOS applications, with the Android and iOS app launching recently.

    But the larger shift has been in how Tela thinks about business data.

    Rather than simply showing business owners numbers, the team wants Tela to help them understand those numbers.

    A business owner might know that sales have fallen by 20 percent compared with the previous week. Tela is being built to go beyond presenting that information by helping answer questions such as why sales are falling and what the business owner could do to improve them.

    The team describes this as building Tela on AI rather than simply adding AI as a feature.

    The goal is to turn business data into insights that entrepreneurs can understand in clear language, particularly for business owners who already have numerous responsibilities competing for their attention.

    For Tela, data is therefore not simply something a business collects. It is part of the technology that can drive the business forward.

    Bootstrapping the journey

    The company has also grown without external funding.

    According to the founders, the  co-founders have funded Tela themselves from the beginning and continue to bootstrap the business.

    That has meant building with a lean team and making the most of the resources available to them.

    For James, one of the biggest lessons from the journey has been the resilience required to keep building.

    He described staying together as a team and reaching this stage without external funding as one of the things he is most proud of.

    For a startup still navigating product development, adoption and market expansion, that resilience has become an important part of Tela’s story.

    Partnerships, payments and early traction

    As Tela has evolved, partnerships have also played a role in strengthening the platform.

    The company identified its partnership with Anchor as an important milestone, particularly around payments. The founders said the partnership helped improve payment processing and contributed to better reviews and increased adoption.

    Tela also processes payments for small businesses, and the team says transaction volumes have been increasing.

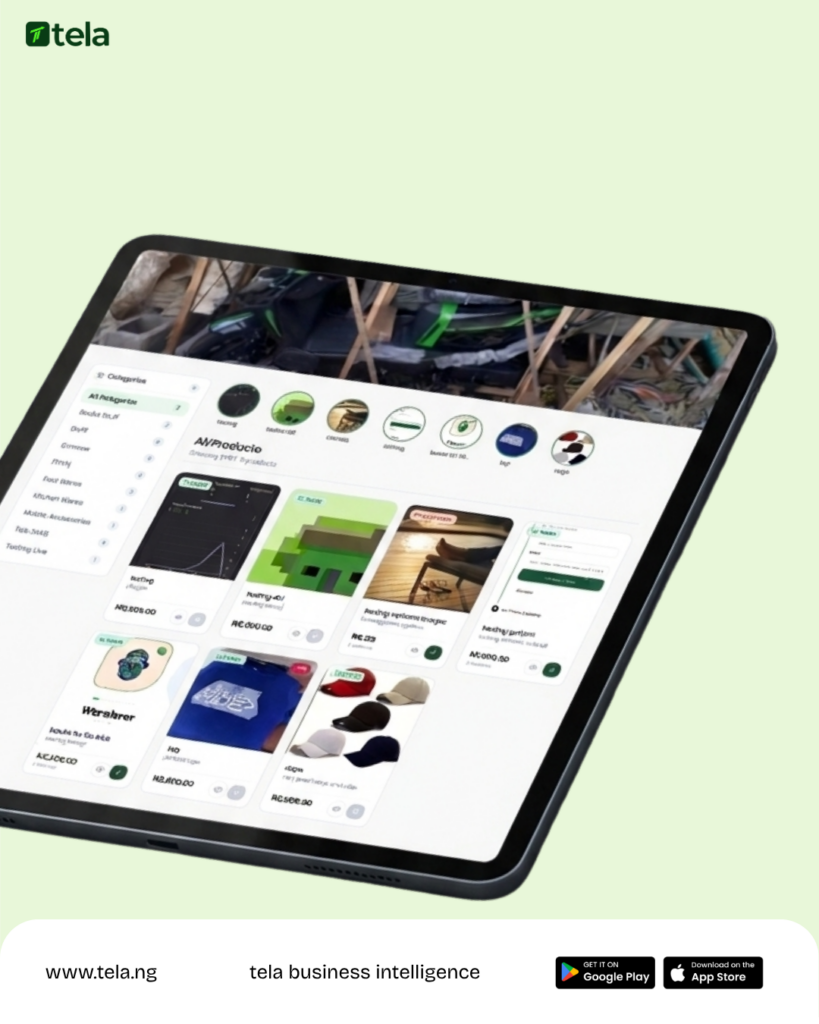
    More recently, the company introduced a storefront feature that allows small businesses to sell directly through the platform using payment links.

    While the team had not yet begun actively pushing the storefront feature at the time of the interview, it represented another step towards making Tela a more comprehensive platform for businesses.

    The company is also beginning to see adoption of its mobile product. Tela says it has surpassed 1,000 active users on its mobile app within its first three months, with more than 3,000 users overall.

    From business intelligence to an intelligent operating system

    Tela’s ambitions extend beyond its current product.

    The founders want the company to eventually become an intelligent operating system for growing and established businesses.

    That means expanding beyond its current capabilities and adding more of the tools entrepreneurs rely on to operate their businesses, while continuing to use AI to make those tools more intelligent.

    One of the company’s major upcoming products is a standalone sales AI.

    The team is working towards a system that can automate significant parts of the sales process, from payment and customer conversations to fulfilment, with the intention of allowing business owners to focus on the parts of the process that still require their direct involvement.

    The product is expected to be one of Tela’s major milestones over the coming months.

    Looking beyond Nigeria

    Tela’s ambitions are not limited to the Nigerian market.

    The company plans to expand across Nigeria before moving into other West African markets.

    The founders also indicated that they expect to become open to investment as the business grows and the company prepares for its next stage.

    For now, however, Tela remains focused on building the product, understanding its users and proving that AI can do more for small businesses than simply automate tasks.

    Its larger bet is that the next generation of business software should not only record what happened in a business, but help business owners understand why it happened and what they can do next.

    That is the direction Tela is taking as it works towards becoming an intelligent operating system for African businesses.

  • Fintech and Chill Is Creating Space for the Stories Nigerian Builders Rarely Tell

    Builders in Fintech (BIF) will host the maiden edition of Fintech & Chill in Lagos on June 27, bringing together founders, operators, builders, and thought leaders for conversations around the theme: “Beyond the Hype: The Reality of Building in Fintech.”

    At a time when many conversations in tech are dominated by funding announcements, expansion plans, and success stories, the event aims to spotlight the realities that often remain hidden. These include the setbacks, pivots, difficult decisions, and lessons that come with building fintech products and companies in Nigeria over the long term.

    But why are such builder-to-builder conversations important, and why shouldn’t they be too formal?

    1. Success Stories Rarely Tell the Whole Story

    African tech has come a long way, and it goes without saying that Nigeria is Africa’s leading technology hub, with Lagos alone attracting billions of dollars in investment and producing globally recognised companies.

    Funding rounds, unicorn announcements, expansion plans, and breakthrough products have become familiar headlines. But headlines rarely tell the full story.

    With such big wins across social media, it is easy to believe that building in tech is a straight line from idea to product-market fit, followed by growth and international expansion. But anyone who has spent time building knows that in reality, products fail, businesses change strategies, teams experience growing pains, customer behaviour evolves, regulations shift, and markets become more competitive.

    For instance, PaidHR CEO Seye Bandele recently revealed that his team shut down the product they had spent 15 months building after receiving expert feedback. It then took another five months to rebuild.

    That was nearly two years of learning, iteration, and difficult decisions before eventually launching into the market. Conversations like that rarely make it to conference stages, social media threads, or media headlines. When they do, they often provide far more value to aspiring builders than another announcement about growth metrics or funding rounds.

    Unfortunately, these experiences are not always shared openly. Companies are under pressure to maintain momentum, attract investors, reassure customers, and retain talent. But when only the wins are visible, younger builders may develop unrealistic expectations, and the ecosystem loses out on valuable lessons.

    Some of the most useful knowledge in tech often comes from understanding what went wrong, what nearly failed, and what had to change before progress was possible.

    2. Builders Need More Than Inspiration

    Inspiration has its place, but builders need more than motivation. People building products, companies, and careers need context, perspective, and stories that reflect the realities they encounter every day.

    Hearing how a founder navigated regulatory uncertainty, how an operations team managed rapid growth, or how a product leader responded when an initial strategy failed can be far more valuable than another polished success story.

    These conversations create room for nuance. They remind us that growth is messy, progress takes time, and setbacks are often part of the process rather than evidence of failure.

    More importantly, they help people make better decisions. For instance, a product manager struggling with adoption challenges may learn more from hearing how another team navigated similar issues than from a motivational keynote.

    An early-stage founder may benefit more from understanding why a strategy failed than from hearing a polished success story stripped of its setbacks.

    This is one reason communities and ecosystem events are important. They create spaces where lessons can be shared openly and where builders can learn from one another’s experiences rather than repeating the same mistakes.

    3. Building Is Bigger Than Founders

    When people talk about tech, the spotlight often falls on founders. While founders play a critical role, ecosystems are built by far more than a handful of visible individuals.

    Think of the engineers who keep systems running, the designers who shape experiences, operators who ensure execution happens, marketers who connect products with customers, compliance professionals navigating regulations, and community builders who bring people together.

    Yet these contributions rarely receive the same attention as founders and CEOs. Some of the most important decisions affecting product quality, customer trust, and operational excellence are made by people whose names never appear in press releases.

    Recognising these contributions creates healthier conversations and stronger communities. It also broadens our understanding of what it means to be a builder.

    Which is perhaps why some of the best conversations in tech happen when titles are left at the door, and everyone is simply talking builder to builder.

    4. Stronger Ecosystems Are Built on Shared Lessons

    As the industry becomes more competitive and expectations continue to evolve, collaboration and knowledge sharing will matter more than ever.

    Healthy ecosystems are not built solely on success stories. They are built on trust, transparency, and a willingness to share both positive and painful lessons.

    This does not mean celebrating failure for its own sake or becoming cynical about the future. Instead, it means embracing the idea that honest conversations are just as important as ambitious dreams when building.

    Because when builders share what they have learned, everyone benefits. As the ecosystem matures, builders need more than networking opportunities and inspirational speeches. They need spaces where difficult questions can be asked, assumptions challenged, and experiences shared openly.

    They need opportunities to hear from founders who made costly mistakes, operators who scaled teams, marketers who navigated growth challenges, and product leaders who learned painful lessons.

    These conversations do not always happen on social media. Neither do they always make the headlines. But they are often the conversations that move the ecosystem forward.

    5. Tech Doesn’t Always Have to Be Serious

    In many ways, the best conversations in tech are rarely the most “serious” ones. They are the candid discussions that happen without fancy titles in a space where builders are comfortable enough to share their stories.

    Those conversations are insightful, relatable, and sometimes, even funny. Because building is already serious work and builders can chill too.

    Where Are Builders Sharing Such Stories?

    On June 27, BIF will bring those conversations under one roof in Lagos through the maiden edition of Fintech & Chill.

    “Beyond the Hype” by BIF is an invitation for builders to speak more openly about what building really looks like, including the wins and the realities that accompany them. Because beyond the funding announcements and success stories are the stories builders rarely tell — and those stories may contain the lessons that matter most.

    Attendees will hear firsthand from some of the industry’s most experienced operators and leaders, including Feranmi Ajetumobi, Director of Growth at Timon (formerly Flutterwave and Cowrywise); Kazeem Noibi, CTO at Cray (formerly VP of Technology at FairMoney and CTO at Fincra); and Tokunbo Omonubi, Chief Product Officer at Remita, alongside other founders, builders, and thought leaders shaping the future of technology in Nigeria.

    And yes, there will be networking, interactive games, and enough builder stories to remind everyone that nobody really has it all figured out.

    Because Fintech & Chill isn’t just about fintech. It’s about the “chilled” people building it.

    Be a part of Fintech & Chill 2026

    📅 June 27, 2026
    📍 Lagos, Nigeria
    🎟 Early Bird Tickets: ₦5,000

    Secure your seat and join the conversation.

  • Peerless Launches SeaBaas Lite to Transform Core Banking for Nigerian Microfinance Institutions

    Peerless Launches SeaBaas Lite to Transform Core Banking for Nigerian Microfinance Institutions

    Peerless, a modern enterprise technology company, has officially announced the launch of SeaBaas Lite. This core banking solution is built to support the digital transformation of microfinance institutions (MFIs) and fintechs across Africa.

    The product represents a standardized version of the company’s flagship SeaBaas core, designed for rapid deployment and operational efficiency.

    The Nigerian financial sector currently faces significant infrastructure hurdles. High capital expenditure on hardware, foreign exchange volatility affecting software maintenance, and the complexity of local regulatory compliance have created barriers for many institutions.

    SeaBaas Lite addresses these challenges by offering a cloud-native platform hosted on Huawei Cloud with local data residency. This ensures that Nigerian financial data stays within the country, meeting the requirements of the Central Bank of Nigeria (CBN) and the Nigeria Data Protection Regulation (NDPR).

    SeaBaas Lite is built on an API-first modern core. This technical foundation allows for seamless integration with external channels, facilitating automatic verifications and faster customer onboarding. By removing the need for manual data entry and disjointed verification processes, institutions can reduce their transaction processing time by 60%.

    The platform also solves a major pain point for compliance officers through built-in regulatory reporting templates. These templates are pre-mapped to local requirements, allowing banks to generate reports for regulators with a single click. This automation reduces the risk of manual errors and the potential for regulatory fines.

    Data is a central component of the new offering. SeaBaas Lite provides robust analytics that give banks rich insights into customer behavior. These data-driven tools help institutions move beyond simple record-keeping to identify new revenue opportunities and improve credit scoring models.

    “Peerless is on a mission to remove the high barriers of entry that have historically held back African financial institutions,” says Dr. Joachim Adenusi, Co-Founder and CEO of Peerless. “SeaBaas Lite gives MFBs and regional banks access to world-class infrastructure without the heavy price tag of legacy systems. We believe every institution deserves a core that supports growth instead of hindering it.”

    Support remains a key differentiator for Peerless. Unlike global competitors that often manage support from different time zones, Peerless maintains a top-quality technical and customer support team based in Lagos. This proximity allows for one-hour response times and a deeper understanding of local integration rails and network conditions.

    The track record of the SeaBaas infrastructure is substantial. The platform has served over 12 million end users and processed more than 4 billion transactions. These operations have led to over $30 million in operational savings for Peerless customers. The system maintains a 99.99% availability rate, providing stability even during peak transaction periods.

    Olumide Odeyemi, Marketing & Growth Manager at Peerless, notes that the transition from traditional hardware ownership to cloud access is a necessity in the current economic climate. “The cost of maintaining rigid legacy systems consumes budgets that should go toward innovation. SeaBaas Lite moves these costs from a heavy upfront investment to a predictable operational expense.”

    SeaBaas Lite is now open for subscription. Interested institutions can visit https://bepeerless.co/product/seabaaslite to learn more about the platform’s capabilities and the 30-day deployment promise.


    About Peerless

    Peerless is a modern enterprise technology company purpose-built to support the digital transformation of institutions in emerging markets. With offices in Nigeria and the UAE, Peerless provides core digital infrastructure including core banking software, business process automation, and customer relationship management tools.

  • The African Tech Brand Quietly changing lives : Paystack

    The African Tech Brand Quietly changing lives : Paystack

    When I think about the African tech brand that has quietly made life easier for thousands of creatives, small business owners, and dreamers like me, Paystack is the first name that comes to mind. It’s funny because I didn’t start out paying attention to fintech at all.

    I just wanted to understand why so many business pages on Instagram were suddenly taking payments smoothly without all the usual back-and-forth. Somewhere along the line, the answer kept pointing back to one company: Paystack.

    My first real interaction with the brand wasn’t even as a business owner. It was as a customer. I remember trying to pay for a virtual class and expecting the usual stress-failed transactions, double debits, or the “network not available” message.

    But the payment went through instantly, and the receipt hit my email before I could even refresh the page.

    It was such a small moment, but it made me pause. In this country, where simple things often become complicated, that small moment of ease meant something.

    The more I paid attention, the more I realized how deeply Paystack is woven into the daily hustle across Africa.

    The vendors who rely on payment links. The creators who send invoices. The startups that feel “official” because they have a proper checkout page. Even NGOs and schools use it now.

    Paystack somehow manages to be present but not loud , almost like a quiet backbone that keeps so many ideas alive.

    What I love most is how simple they make things feel. You don’t need to be tech-savvy to use it. You don’t need a big business. You don’t even need a website.

    There’s something empowering about that the idea that anyone with a skill or a passion can start collecting payments and building something real.

    And of course, the global recognition they’ve gotten, especially after their acquisition by Stripe, made me genuinely proud. It felt like a win for everyone who believes Africa can build world-class technology.

    But beyond the headlines and the milestones, Paystack represents something personal to me: possibility.

    The possibility that African problems can be solved by African innovators. The possibility that a simple idea can transform how we work and create.

    Paystack may be a fintech company, but to me, it’s a reminder that progress doesn’t always have to be loud. Sometimes, it’s the quiet systems running in the background that change the most lives.

    That’s why Paystack is the tech brand I love.

  • Chams Mobile is quietly building real solutions for Nigeria

    Chams Mobile is quietly building real solutions for Nigeria

    I still remember the first time someone mentioned Chamsmobile to me. It was during a casual conversation about digital payments and identity systems in Nigeria, and a friend said, “Have you checked what Chamsmobile is doing?

    They are not loud, but they’re doing real work.” Out of curiosity, I went online to see for myself, and honestly, that small search opened my eyes to a brand that deserves far more attention than it gets.

    What I love about Chamsmobile is that they are building solutions for realities we face every day in this country, not fantasies.

    Many tech companies chase hype; Chamsmobile builds quietly for people who need technology the most: market women, transport workers, SMEs, civil servants, and communities usually left out of the main conversation.

    One thing that really stood out to me is their focus on digital identity and financial inclusion. In a country where a simple thing like verifying someone’s identity can delay jobs, stop access to credit, or complicate business transactions,

    Chamsmobile found a way to simplify it with their Kegow platform. It’s not just about transferring money. It’s about helping people prove who they are, opening accounts easily, and accessing financial services without stress.

    I also respect how they operate. They don’t try to be everywhere at once; instead, they focus on solving real administrative and financial gaps in Nigeria.

    For example, the way they’ve built partnerships with government agencies and private organizations shows that they understand the Nigerian system deeply. They’ve also created room for agents and small business owners to earn through their digital services, and for me, that’s one of the most practical ways a tech brand can empower ordinary people.

    Another thing I admire is the trust they’ve built over the years. In a space where many fintechs rise fast and crash even faster, Chamsmobile is consistent.

    They don’t make noise, but they deliver. They’ve been part of Nigeria’s digital identity journey long before it became trendy, with the help of their parents’ company, Chams Hold Co, and they’ve stayed committed to it through every challenge.

    Chamsmobile makes me proud because they represent what African tech should be: innovation rooted in real problems, solutions created with Nigerians in mind, and a quiet confidence that speaks louder than hype. They may not always trend on social media, but they are impacting lives in a way that truly matters.

    For me, that’s the kind of tech brand worth celebrating.

  • The African Fintech Library: Preserving the Institutional Memory of a Continent in Motion

    The African Fintech Library: Preserving the Institutional Memory of a Continent in Motion

    In the African tech ecosystem, the greatest barrier to scale isn’t always capital or talent: it’s the “Knowledge Gap.”

    For a decade, the “how-to” of African fintech has existed in silos. Valuable lessons on navigating the Central Bank of Nigeria (CBN), managing cross-border liquidity in the EAC, or scaling credit in South Africa are often trapped in private WhatsApp groups or lost when an operator switches roles.

    Today, Builders in Fintech are changing that. With the launch of the African Fintech Library (AFL), the ecosystem finally has a structured, durable archive for the hard-won lessons of its builders.

    Beyond the Informal: Why Structure Matters

    The AFL didn’t emerge from a vacuum. It was born from a recurring observation: Africa’s fintech sector is projected to grow 5x by 2028, yet its “institutional memory” is scattered.

    “Valuable operational and regulatory lessons are being generated every day,” the AFL team notes. “But they are rarely captured in a format that outlives the moment.”

    The Library is the intentional answer to this problem. It is designed to preserve knowledge before it disappears, making it accessible to a founder in Senegal who needs to understand the compliance mistakes made by a predecessor in Ghana.

    One Archive. 10,000 Practical Insights.

    The vision for the AFL is as bold as the sector it serves. It isn’t just a blog; it is a Structured Knowledge Infrastructure.

    Think of it as the “Reference Manual” for the African context. The Library covers the critical, often unglamorous, pillars of the industry:

    • Payments & Infrastructure: The “plumbing” of how money actually moves across borders.
    • Regulation & Governance: Navigating the shifting sands of continental policy.
    • Risk & Credit: Managing the math behind Africa’s lending boom.

    Built by Practitioners, for Builders

    The most distinctive feature of the AFL is its authorship. Every guide is written by real world practitioners, the people who have sat in the rooms where the decisions were made.

    By moving from “theory” to “hands-on experience,” the AFL levels the playing field. Emerging talent and first-time founders no longer need to rely solely on “private circles” to understand the nuances of the market. They now have a central publication that offers expert knowledge backed by thorough research and lived experience.

    A Call to the Ecosystem: Contribute Your Story

    The AFL is a living asset. As the ecosystem evolves, so must the Library. The team is calling on builders across the continent to share their practical knowledge.

    The process is rigorous but rewarding:

    1. Write: Draft a publication ready guide based on a topic you know in theory and practice.
    2. Submit: Your work undergoes a 2–4 week review by the Builders in Fintech editorial team.
    3. Preserve: Once live, your insights become a permanent part of the continent’s fintech history.

    The ATJ Perspective: Why We Are Amplifying This

    At African Tech Journal, we believe that Structured Knowledge = Faster Innovation. The launch of the African Fintech Library marks a new dispensation. It is the moment the African fintech sector stops “reinventing the wheel” and starts building on a foundation of collective intelligence. Whether you are an operator looking to build faster or a student looking to understand the mechanics of money, the AFL is now your primary reference.

    Start Exploring the Archive Today

    Don’t build in the dark. Access the collective memory of the continent’s best builders.

    Visit: www.buildersinfintech.com/afl


  • Is Face ID Really 2FA? Rethinking Biometric Security in Financial Apps

    Is Face ID Really 2FA? Rethinking Biometric Security in Financial Apps

    Financial institutions increasingly use 2-Factor Authentication (2FA) in their mobile apps to protect customer transactions. Traditionally, 2FA combines two different types of verification. This is usually something you know, such as a transaction PIN or one-time password, and something you have, such as your registered phone or a token.

    In many modern transaction flows, after a user enters a transaction PIN or token, the app then requests biometric authentication. This could be Face ID or a fingerprint, depending on the user’s device. While this improves convenience, it raises an important question. Should device-level biometrics really count as a valid second factor for transaction authentication when the verification does not happen within the financialinstitution’s systems?

    How Biometrics Work in Financial Apps

    When a financial app uses Face ID or fingerprint authentication:

    ● The app does not see or transmit the raw biometric data. Instead, it asks the phone whether the biometric presented matches one of the biometrics already enrolled on the device

    ● The biometric data itself is stored securely on the phone, within protected hardware designed for this purpose. The app simply receives a yes or no response from the device. The financial institution never receives the actual fingerprint or facial data.

    This means the institution is relying on the phone’s confirmation rather than directly verifying the user’s biometric identity.

    Can Biometrics Count as a “Second Factor”?

    Traditionally, 2FA is based on using two different categories of authentication:

    1. Something you know, such as PIN or password

    2. Something you have, such as a phone or token

    3. Something you are, such as a fingerprint or face

    On the surface, combining a transaction PIN with Face ID or a fingerprint appears to meet the definition of 2FA. However, there is an important distinction.

    Because the biometric check is performed entirely on the device, the financial institution cannot independently confirm who was authenticated. For this reason, device biometrics are often best viewed as a strong convenience layer rather than a fully independent second factor on their own. They work best when combined with other institution-verified controls, especially for high-risk transactions.

    Security Risks and Edge Cases

    1. Device Access by Another Person

    If another person is able to register their fingerprint or face on a phone, whether intentionally or under pressure, financial apps that rely on biometrics may treat that person as a legitimate user.

    2. Device Trust Over User Identity

    Because the biometric decision comes from the phone, anyone who can unlock the device and add their biometric may be approved during transactions. The financial institution has no visibility into changes made at the device level.

    3. Spoofing and Advanced Attacks

    While modern phones include strong protections, biometric systems are not immune to spoofing attempts such as fake fingerprints or manipulated facial images, especially on older or less secure devices.

    4. Biometrics Cannot Be Changed

    Unlike a PIN or password, biometrics are permanent. If they are compromised, they cannot simply be reset. This makes them riskier as a primary security control over time.

    Is It Safe to Use Device Biometrics as Part of 2FA?

    Benefits

    ● Convenience. Transactions are faster and easier for users.

    ● Device-level protection. Biometric data is stored securely on the phone and is difficult for remote attackers to extract.

    Limitations

    ● Dependence on the device. If a phone is lost, stolen, or compromised, risk increases.

    ● No direct verification. The financial institution cannot confirm who passed the biometric check.

    ● Accuracy limits. Biometric systems can sometimes fail or incorrectly approve access.

    Regulatory and Legal Considerations

    ● Most financial institutions clearly state in their terms that enabling biometric login means any biometric registered on the device may be able to access the account.

    ● Device manufacturers aren’t legally liable for financial fraud from financial app transactions authenticated via device biometrics. Responsibility typically rests with the financial institution’s policies and local financial regulations.

    ● In many regions, financial institutions must still comply with privacy and data protection laws related to biometric use, even when the data is stored only on the device. However, this does not automatically transfer liability to device providers.

    In conclusion, device biometrics add meaningful value by improving convenience and strengthening security at the device level. However, they are not a perfect or fully independent second factor when used alone for transaction authentication. For users, it is important to maintain strong device security, protect phone access codes, and understand how biometric authentication works.

    For financial institutions, biometrics are most effective when used as part of a layered 2FA approach rather than as the sole line of defense.

    By Sunny Ogbari

  • I said goodbye to scam exchangers, a Raenest app story

    I said goodbye to scam exchangers, a Raenest app story

    N500/$ is the rate I’ll use to exchange the funds. Na my account you take collect am.”

    If you’ve freelanced since the days of oDesk and Elance, you’ll recognise this. It’s what so-called exchangers say to freelancers trying to receive payments from clients worldwide.

    Some exchangers are honest, but many are crooks. They take a large cut of freelancers’ earnings or scam them entirely. It’s shocking!

    I fell victim for years. Freelance platforms then updated to allow direct deposits to Africa. FinTech companies like Raenest emerged, enabling us to be paid in any currency.

    Raenest has addressed the scammer-exchanger issue with popular ACH accounts and useful virtual cards.

    Here are five reasons why I believe they will continue to thrive:

    Timely Free Deposit Offers: I’ve signed up with other fintech companies, but none have offered free payment deposits. My ‘grey’ matter just doesn’t have any memory of it 🙂


    Since joining Raenest, I’ve received many free deposit offers. FinTechs usually charge fees for operational costs and regulations. But with Raenest, my USD, GBP, or EUR deposits periodically come in full, with no fees.

    This shows their commitment to helping global earners keep every cent. I think it’s their most thoughtful ‘gift’ and one of the things I love about the them.

    Cross-border Payments: The distance between Europe and Africa is about 14 kilometers. Although people like Pelumi Nubi have crossed the borders using just their cars, 14km is still a far stretch. Let’s not even fact-check the for America to Africa. Yet, we can send and receive money without traveling that distance! Whether you’re a freelancer or a business in Africa needing payments from the UK, US, or China, Raenest has you covered.

    Stablecoin Integration: Many freelancers want to earn in coins like Ethereum or Tron to handle exchange rate changes. Raenest surprised everyone by announcing stablecoin accounts!

    If you have a USD account, you can easily create a stablecoin wallet. Receive payments in USDT or USDC with competitive exchange rates. Exciting, right? 🤭

    Virtual Cards: Using a virtual credit card has never been cheaper. With Raenest, you can get a virtual card for at a low fee. Fund it easily and use it for subscriptions, courses, or ads!

    Bella’s Exclusive Perks: Raenest has launched ‘Raenest Perks’. This offers special discounts for freelancers and business owners. Whether you need groceries or the latest Adidas shoes at 15% off, Raenest is your go-to.

    In conclusion, business development is key to success. Raenest understands its customers and continues to develop strategies to meet their needs.

    If you’re a freelancer, content creator, or running a business in Africa, visit Raenest today at www.raenest.com. Enjoy hassle-free payments and send money to over 40 countries!

  • My first dividend alert from Bamboo changed everything

    My first dividend alert from Bamboo changed everything

    I got a credit alert on Friday, and it completely surprised me. At first, I thought it was just a random notification. But when I checked properly, I realized it was my first-ever dividend payout, from one of the stocks I invested in through Bamboo.

    That small moment made everything feel real, like, “Wow, I’m actually investing.”

    My interest in investing started about two years ago, even though I didn’t fully understand it then. Last year at my former workplace, a few of us, the ladies, got into a conversation about savings, wealth-building, and different investment apps.

    Someone mentioned Bamboo, and we all downloaded it on the spot. We tried setting it up that day, but something came up for me, and I didn’t complete my registration. The excitement faded, and life moved on.

    Earlier this year, I started seeing people on X (Twitter) talk about investment again. I love reading those conversations, especially when they break things down in simple ways.

    Bamboo kept coming up, and because I had interacted with it before, I decided to go back to it. This time, I completed my setup and began investing, even though I wasn’t fully consistent and didn’t understand everything at first.

    What made it easier is how simple the Bamboo app is.

    The interface is clean, clear, and beginner-friendly. You can see your stocks, track your money, and understand what’s happening without feeling confused. And even though I didn’t learn from any official community, I picked up so many helpful tips from regular people sharing their experiences on X, things like how dividends work or how to navigate certain features.

    But nothing prepared me for the feeling of seeing that dividend alert on Friday. The amount wasn’t the point.

    What mattered was the realization that something I invested in actually grew and returned value. It felt like a small victory, but a very meaningful one.

    Bamboo stands out to me because it makes investing accessible. It brings global stocks closer and makes the whole process simple enough for anyone who is just starting the journey.

    And that first dividend? It gave me the motivation to keep going.